How to Navigate Growth Funding: 2026 US Capital Benchmarks, Term Sheet Mechanics, and Dilution Math
To growth navigate funding effectively in the United States, operators must align their unit economics with the right tier of the capital stack: non-dilutive credit lines for predictable working capital, venture debt for runway extension between priced rounds, or institutional growth equity for market expansion. Companies generating between $3 million and $25 million in Annual Recurring Revenue (ARR) face a strict bifurcation in capital access. Founders who raise priced equity to fund short-term inventory or customer acquisition pay permanent ownership costs for temporary balance sheet needs.
Capital markets enforce strict underwriting discipline on mid-stage and growth-stage enterprises. Before signing a term sheet or credit agreement, finance leads must audit how option pool expansions, warrant coverage, financial covenants, and liquidation preferences alter net founder payouts upon exit.
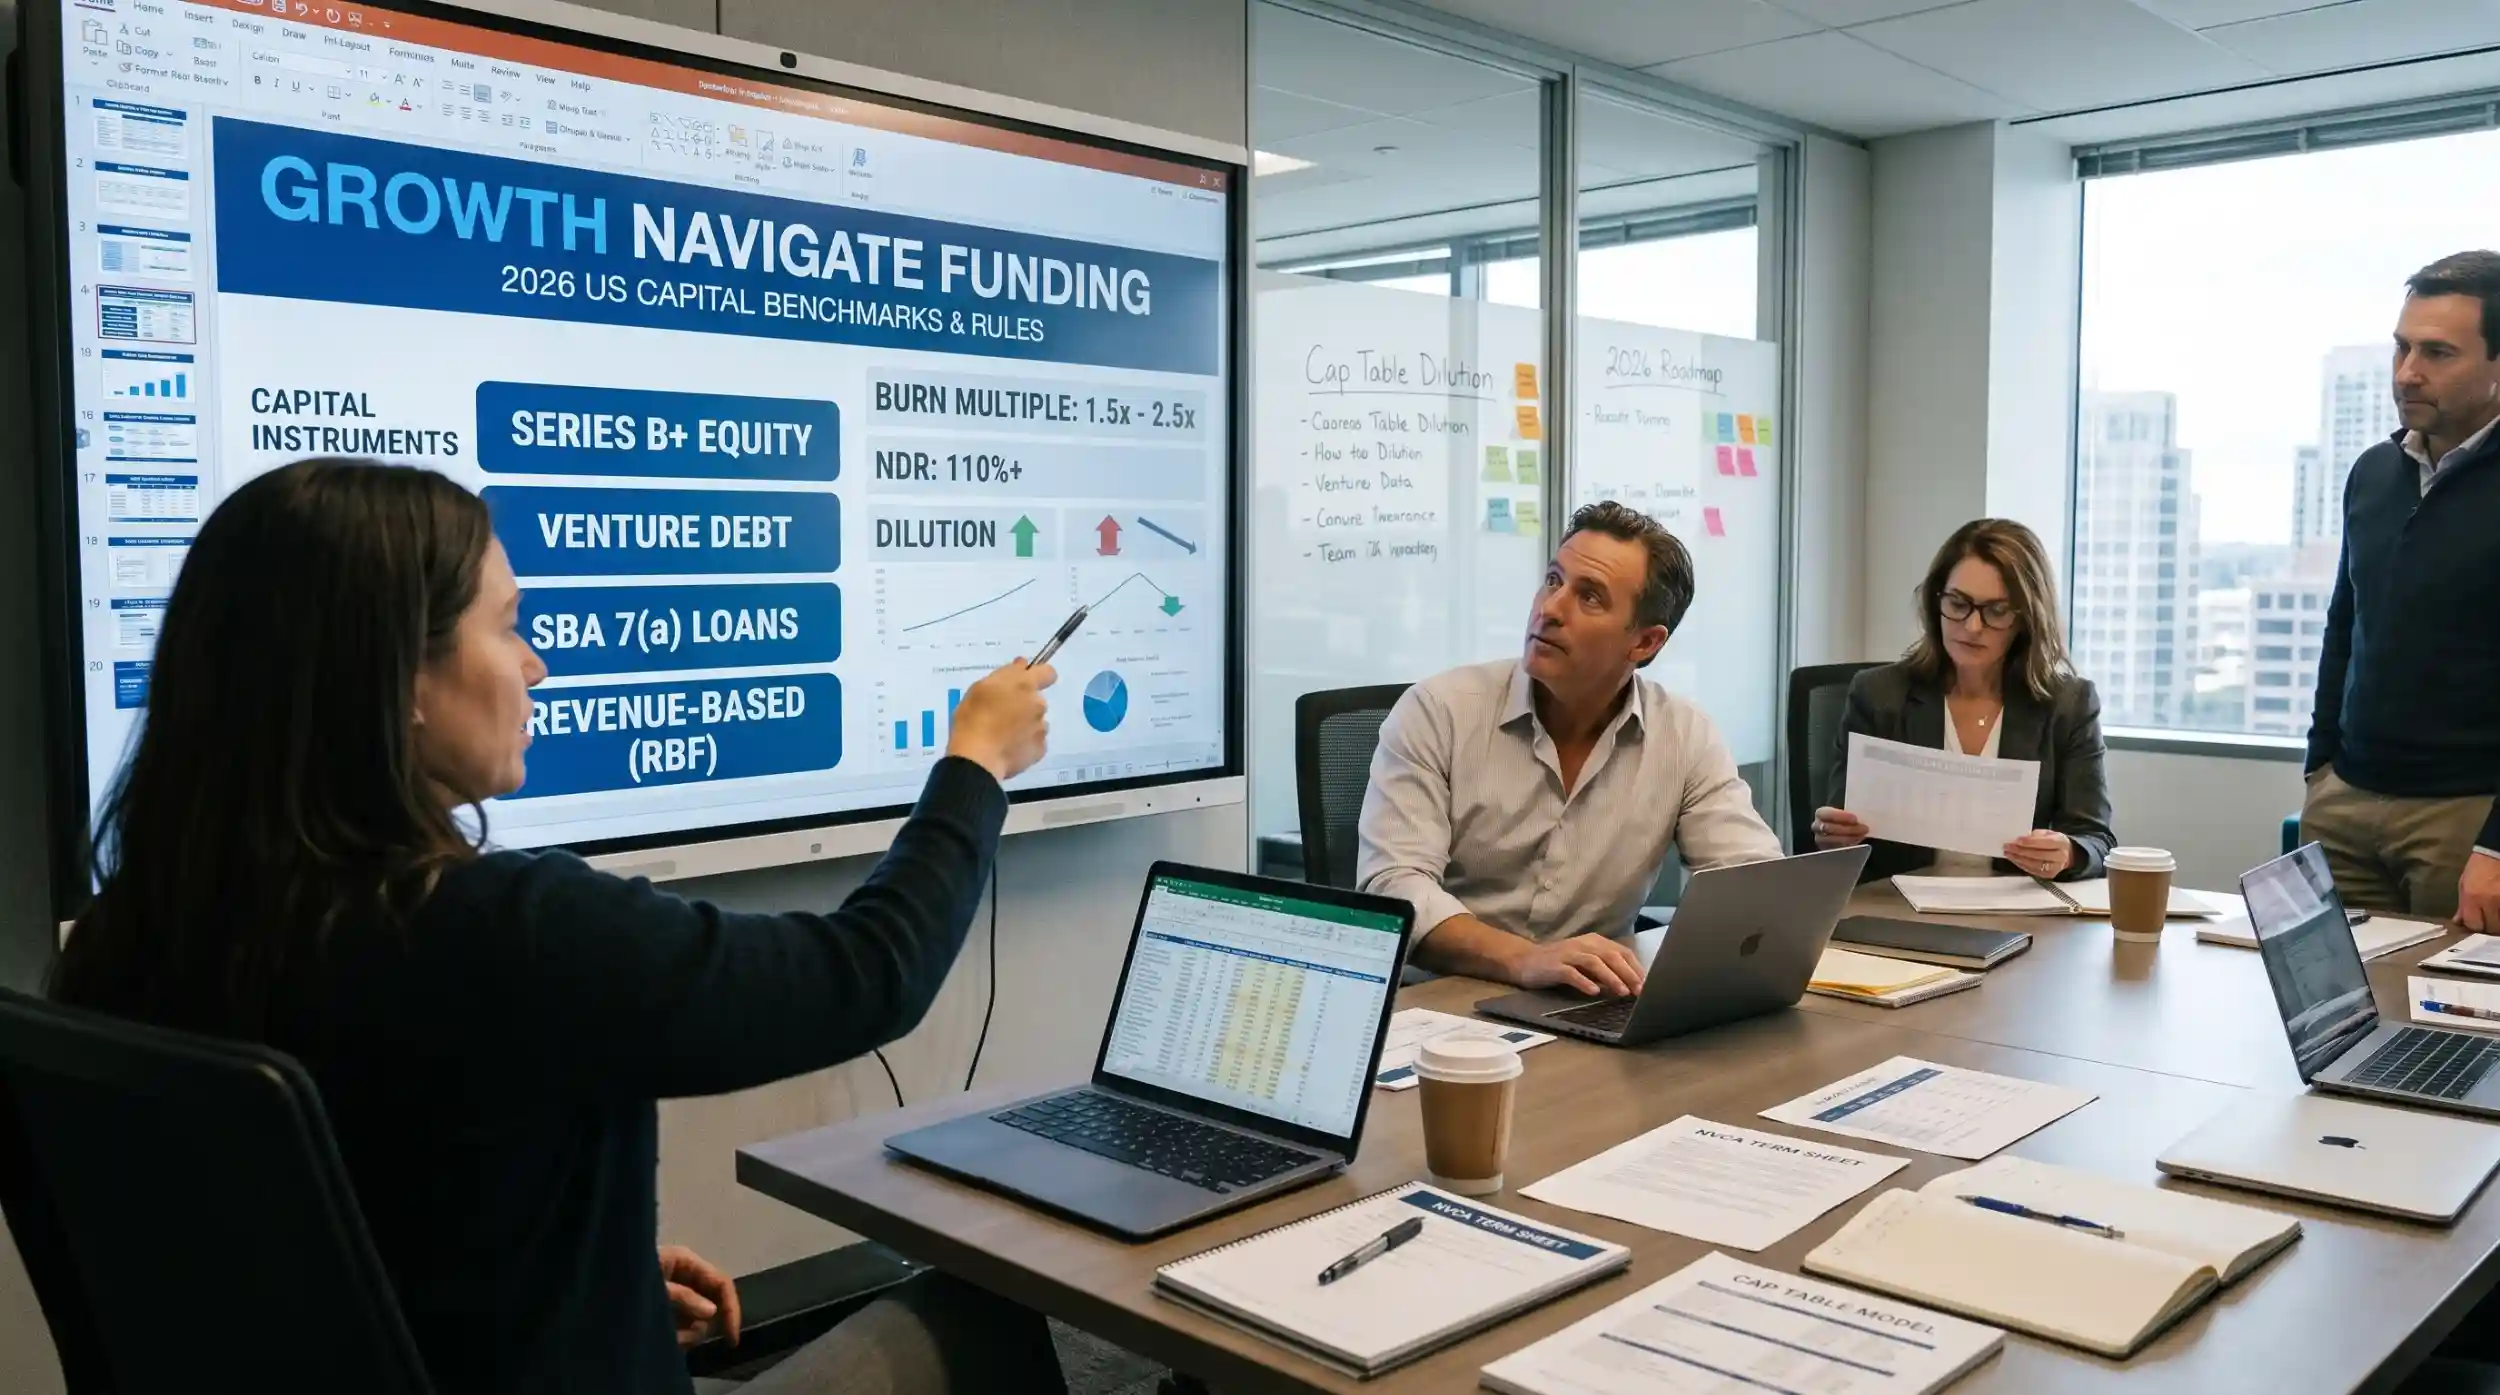
US Growth Funding Instruments: 2026 Benchmark Summary
| Capital Instrument | Typical Check Size | Cost of Capital / Dilution | Core Underwriting Threshold | Governing Framework / Statutory Rule |
| Growth Equity (Series B/C+) | $10M to $75M+ | 12% to 25% equity dilution per round | $5M+ ARR, Net Dollar Retention above 110%, positive contribution margin | SEC Regulation D (Rule 506b/506c) & NVCA Model Legal Documents |
| Venture Debt (Term Loan) | $2M to $20M | SOFR + 4.5% to 8.5% interest; 0.5% to 2.0% warrant coverage | Recent institutional equity raise; 12 to 18 months cash runway | Uniform Commercial Code (UCC) Article 9 Senior Secured Lien |
| Revenue-Based Financing (RBF) | $250K to $5M | 6% to 12% flat factor fee on principal advanced | $50K+ monthly recurring revenue; gross margins above 60% | Commercial Revenue Purchase Agreement (non-FDIC commercial contract) |
| SBA 7(a) & 504 Growth Loans | Up to $5M ($5.5M for 504 manufacturing) | Prime + 2.25% to 4.75% (7a); ~5.5% to 6.8% fixed debenture (504) | 1.15x+ Debt Service Coverage Ratio (DSCR); personal guarantee from 20%+ owners | 13 CFR Part 120 (Small Business Administration Business Loans) |
| Asset-Based Lending (ABL) | $1M to $30M | SOFR + 2.0% to 4.5% floating rate | Borrowing base of 80% to 85% eligible A/R (under 90 days past due) and 50% inventory | UCC-1 Blanket or Specific Collateral Filing & Field Exam Audit |
Underwriting Thresholds: What Institutional Investors Audit First
Capital providers ignore top-line pitch decks once due diligence begins. Analysts immediately reconstruct the general ledger and billing cohorts from raw accounting exports and bank statements.
Three operational metrics dictate whether a company secures tier-one growth terms or punitive structured financing:
-
The Burn Multiple: Calculated by dividing Net Burn by Net New ARR added in a given period. A burn multiple below 1.5x signals efficient capital deployment. When the burn multiple exceeds 2.5x, institutional growth funds either decline to bid or demand structured downside protection.
-
Net Dollar Retention (NDR) and Logo Churn: Growth equity underwriters evaluate cohort stability across 12-month and 24-month windows. For B2B software and subscription models, an NDR exceeding 110% proves that expansion revenue offsets gross churn. High gross logo churn—greater than 2% per month for mid-market accounts—disqualifies borrowers from unsecured credit lines because the underlying recurring revenue asset decays faster than the loan amortization schedule.
-
LTV-to-CAC Payback Period: Total Sales and Marketing expense (fully burdened with payroll, commissions, and tooling) divided by new gross margin added must pay back within 12 to 18 months. If customer acquisition payback stretches beyond 24 months, scaling via high-interest debt triggers a liquidity crunch before cohort cash flows turn positive.
Matching the Capital Stack to Operational Use Cases
Misallocating capital types is the primary cause of unnecessary cap table compression. Every dollar entering a business carries an explicit maturity date or an implicit equity compound rate.
Priced Growth Equity (Series B, Series C, and Private Equity Minority Stakes)
Growth equity finances non-linear bets with uncertain payback timelines: multi-year R&D cycles, international market entry, or strategic M&A roll-ups. Offerings in the United States rely on private placement exemptions under SEC Regulation D (specifically Rule 506(b) for up to 35 non-accredited purchasers alongside accredited investors, or Rule 506(c) permitting general solicitation exclusively to verified accredited investors). Issuers must file Form D with the SEC within 15 days after the first sale of securities and comply with state Blue Sky notice filings.
Senior and Subordinated Venture Debt
Venture debt functions as an insurance policy or a bridge to hit a higher valuation milestone prior to an equity round. Lenders typically size facilities at 20% to 35% of the most recent equity round. Unlike commercial bank loans underwritten against historical EBITDA, venture lenders underwrite against the “equity support” of existing venture capital syndicate members and remaining cash runway.
These facilities split into an interest-only (I/O) period (typically 6 to 18 months) followed by a straight-line principal amortization period (24 to 36 months). Once the amortization cliff begins, monthly principal plus interest payments drain cash rapidly.
SBA 7(a) and 504 Facilities for Non-Venture Growth
Profitable lower-middle-market companies operating without institutional venture backing frequently utilize federally guaranteed loans through the U.S. Small Business Administration (SBA).
-
SBA 7(a) Loans: Capped at $5 million in gross loan proceeds. Funds support working capital, partner buyouts, equipment, and commercial real estate. Terms extend up to 10 years for working capital and 25 years for real estate.
-
SBA 504 Loans: Structured for fixed heavy assets (owner-occupied real estate or long-life machinery). A Certified Development Company (CDC) provides up to 40% of the project cost (capped at $5 million, or $5.5 million for manufacturing and energy public policy projects) backed by a 100% SBA-guaranteed debenture, while a private bank funds 50% as a senior first-lien loan and the borrower contributes 10% equity.
Both SBA programs mandate an unconditional personal guarantee (SBA Form 148) from every individual holding 20% or more equity in the borrowing entity. Venture-backed startups rarely qualify for SBA programs due to affiliation rules under 13 CFR 121.103, which aggregate the employee headcount and revenue of controlling portfolio companies when investor protective provisions cross the threshold of negative control.
Term Sheet Mechanics That Erode Founder Payouts
Headline pre-money valuation is a vanity figure if structured terms strip common shareholders of proceeds during a modest exit. Legal counsel and CFOs must scrutinize four contractual clauses modeled in standard National Venture Capital Association (NVCA) documents.
1. Liquidation Overhang and Participation Rights
Standard institutional terms call for a 1x non-participating preferred liquidation preference. In a sale, preferred investors choose the greater of their invested principal back (1x) or their pro-rata conversion into common stock.
In tightened credit environments, investors introduce participating preferred shares or multiple liquidation preferences (1.5x to 2x). With full participation (“double-dipping”), the investor collects their 1x principal off the top of the exit proceeds and receives their pro-rata percentage of the remaining pool alongside common shareholders. If a company raises $40 million on a 1x participating preferred structure and sells for $60 million while investors own 40% of the cap table, preferred holders take $40 million first plus 40% of the remaining $20 million ($8 million), leaving $12 million for founders and employees.
2. The Option Pool Shuffle
Growth investors routinely require an unallocated employee stock option pool (ESOP) equal to 10% to 15% of the post-money capitalization. When the term sheet specifies that the option pool expansion comes out of the pre-money valuation, existing shareholders absorb 100% of the dilution required to top up the pool before the new investor’s price per share is calculated. Negotiating a hiring plan bottom-up—identifying exact executive roles and equity grants needed over the next 18 months—frequently trims the required pool expansion from 15% down to 7%, saving founders several percentage points of ownership.
3. Anti-Dilution Ratchets
Preferred stock includes price-based anti-dilution adjustments that trigger if the company raises a future round at a lower share price (a “down round”).
-
Broad-Based Weighted Average: The industry norm. It adjusts the conversion price of prior preferred shares using a formula that accounts for both the lower price of the new round and the relative dollar size of the new issuance compared to the entire fully diluted capitalization (including options).
-
Full Ratchet: Reprices 100% of the prior preferred investor’s shares down to the exact price of the new down round, regardless of whether the company issued ten shares or ten million shares at the lower price. Full ratchets wipe out common equity unless paired with a “pay-to-play” provision forcing existing investors to participate pro-rata in the down round to retain their anti-dilution protection.
4. Financial Covenants in Debt Agreements
Credit agreements contain affirmative, negative, and financial maintenance covenants. The two most hazardous maintenance covenants for scaling businesses are:
-
Minimum Liquidity Covenant: Requires the borrower to maintain unrestricted cash in controlled accounts (governed by a Deposit Account Control Agreement, or DACA) equal to a fixed dollar amount or a multiple of monthly cash burn (e.g., 6 months of trailing burn). Breaching this threshold constitutes an Event of Default, allowing the lender to sweep cash directly from the bank account or charge default interest (typically an extra 300 to 500 basis points).
-
Performance-to-Plan (Minimum Revenue/EBITDA) Covenant: Requires the borrower to hit 75% to 85% of board-approved quarterly revenue or EBITDA projections. If a major enterprise contract slips by two weeks across a quarter-end boundary, the company falls into technical default.
Capital Stack & Dilution Modeling: Step-by-Step Calculation
Before executing a financing commitment, build a sensitivity model comparing the effective cost of equity dilution against the fully loaded cash and equity cost of venture debt.
Consider a US B2B company at $10M ARR raising $15,000,000 to reach profitability prior to an anticipated $150,000,000 exit in 36 months. The company currently has 10,000,000 fully diluted shares and a $60,000,000 pre-money valuation ($6.00/share).
================================================================================
SCENARIO A: $15M PRICED EQUITY ROUND (WITH 5% PRE-MONEY OPTION POOL TOP-UP)
================================================================================
1. Pre-Money Valuation:                     $60,000,000
2. New Investment Amount:                   $15,000,000
3. Post-Money Valuation:                    $75,000,000
4. Existing Fully Diluted Shares:           10,000,000
5. Required New Option Pool Top-Up:         5.0% of Post-Money ($3,750,000 value)
6. Effective Pre-Money for Existing Shares: $60,000,000 - $3,750,000 = $56,250,000
7. New Share Price:                         $56,250,000 / 10,000,000 = $5.625 / share
8. New Investor Shares Issued:              $15,000,000 / $5.625 = 2,666,667 shares (20.0%)
9. Option Pool Top-Up Shares Issued:        $3,750,000 / $5.625  = 666,667 shares (5.0%)
10. Total Post-Money Shares:                13,333,334 shares
11. Existing Holders Post-Round Ownership:  10,000,000 / 13,333,334 = 75.0%
12. Value Given Up at $150M Exit (25%):     $37,500,000

================================================================================
SCENARIO B: $10M EQUITY + $5M VENTURE DEBT (10% RATE, 1% WARRANT COVERAGE)
================================================================================
1. Equity Raised ($60M Pre / $70M Post):    $10,000,000 (14.29% Investor Dilution)
2. Option Pool Top-Up (Reduced to 3%):      3.0% of Post-Money
3. Existing Holders Post-Equity Ownership:  82.71%
4. Venture Debt Principal:                  $5,000,000 (36-month term, 12m I/O)
5. Total Cash Interest + Closing Fees:      ~$1,120,000 over 36 months
6. Warrant Shares Coverage:                 1.0% of Principal = $50,000 / $5.79 = 8,635 shares
7. Warrant Value at $150M Exit (2.14x):     ~$107,000 (Net of exercise price)
8. Total Cost of $5M Debt Tranche:          $1,227,000 (Cash Interest + Fees + Warrants)
9. Cost of Same $5M Raised via Equity:      7.14% of $150M Exit = $10,714,285
================================================================================
NET SAVING TO EXISTING SHAREHOLDERS IN SCENARIO B: ~$9,487,285
This breakdown shows why CFOs pair smaller equity rounds with modest credit tranches once revenue predictability is established. Raising the final $5 million via equity costs existing shareholders $10.71 million at a $150 million exit; raising that same $5 million via venture debt costs $1.23 million in combined interest, closing fees, and warrant dilution.
Data Room Architecture and Due Diligence Friction Points
Funding processes stall or collapse between term sheet execution and wire transfer when historical compliance gaps surface during third-party legal and accounting audits. Prepare four critical workstreams before opening a virtual data room:
1. GAAP Revenue Recognition (ASC 606 Compliance)
Early-stage startups frequently book annual upfront customer payments as immediate cash revenue. Institutional growth investors and bank auditors require financial statements compliant with FASB ASC 606 (Revenue from Contracts with Customers). Upfront billings must sit on the balance sheet as a Deferred Revenue liability and amortize ratably over the performance obligation period. Additionally, direct incremental sales commissions must be capitalized under ASC 340-40 and amortized over the expected customer benefit period rather than expensed immediately upon payout.
2. Multi-State Sales Tax Nexus Liabilities
Following the U.S. Supreme Court ruling in South Dakota v. Wayfair, Inc., nearly all U.S. states enforce economic nexus laws requiring remote sellers of physical goods—and, in over 20 states, SaaS and digital goods—to collect and remit state sales tax once annual sales in that state exceed $100,000 or 200 transactions. Uncollected historical sales tax is a strict statutory liability that stays with the corporation. Acquirers and growth funds routinely calculate maximum historical tax exposure plus penalties and force the company to place 100% of that amount into a restricted escrow account at closing.
3. Section 409A Valuation and Section 1202 (QSBS) Preservation
Issuing employee stock options below fair market value violates Internal Revenue Code Section 409A, triggering immediate ordinary income tax for the employee plus a 20% federal penalty tax and interest. Companies must maintain a current independent 409A appraisal (valid for 12 months or until a material financing event).
Simultaneously, U.S. C-Corporations should audit their eligibility for Qualified Small Business Stock (QSBS) under IRC Section 1202, which shields early investors and founders from federal capital gains tax on up to the greater of $10 million or 10x their cost basis (or up to $15 million with inflation adjustments for stock issued after recent tax enactments, subject to holding period tiers of 3, 4, and 5 years) if gross assets of the domestic C-Corp did not exceed statutory ceilings (historically $50M, raised to $75M under updated federal small business tax provisions) immediately after the stock issuance. Significant stock redemptions within one to two years of a new issuance can disqualify an entire round from QSBS treatment.
4. Chain of Title on Intellectual Property
Every founder, employee, and third-party contractor who wrote code, designed hardware, or created proprietary data models must have an executed Proprietary Information and Inventions Agreement (PIIA) containing present-tense assignment language (“hereby assigns,” not “agrees to assign in the future”). If a former co-founder or offshore dev shop contributed core architecture without signing an explicit IP assignment, investors will halt closing until the company obtains a quitclaim assignment or rewrites the affected codebase.
Who Should Avoid Institutional Growth Funding (And Hidden Pitfalls)
Not every expanding company belongs on the institutional venture or credit track. Two financing traps regularly destroy solvent mid-market businesses:
-
The Merchant Cash Advance (MCA) Death Spiral: Online fintech lenders aggressively market “24-hour growth funding” structured as Merchant Cash Advances. MCAs are not regulated under state usury caps in many jurisdictions because they are framed as purchases of future receivables. However, daily or weekly Automated Clearing House (ACH) debits combined with factor rates of 1.25 to 1.45 over 6-month payback periods equate to an effective Annual Percentage Rate (APR) between 60% and 180%. Stacking multiple MCAs strips operating cash flow and violates the negative pledge clauses of every senior bank loan.
-
The Over-Capitalization Preference Trap: Accepting a $30 million growth equity check at a $150 million post-money valuation forces the company into a binary outcome. Because institutional funds require a 3x to 5x return on growth checks, investors will block a $120 million acquisition offer using their protective provisions, even if a $120 million sale would make the founders generational wealth. If your total addressable market (TAM) realistically caps out at $100 million to $200 million in enterprise value, fund growth through commercial bank debt, SBA facilities, or retained earnings rather than institutional preferred equity.
Frequently Asked Questions
How much equity dilution is normal in a Series B growth round?
In the US market, Series B growth rounds typically result in 15% to 22% gross dilution to existing shareholders, inclusive of any required pre-money employee option pool expansion. Top-decile companies growing faster than 100% year-over-year with positive cash flow efficiency occasionally command dilution in the 10% to 14% range.
Can a startup get venture debt without institutional VC backing?
Traditional venture debt lenders rarely lend to bootstrapped or angel-backed startups because their underwriting model relies on the “implied put” of institutional venture capital reserves to support the company during a downturn. Bootstrapped companies with at least $3 million in ARR and positive EBITDA should pursue Recurring Revenue Loans (MRR lines) from commercial tech banks or Asset-Based Lending (ABL) facilities backed by accounts receivable instead.
What is the difference between a priced equity round and a convertible bridge note for growth?
A priced equity round sets a fixed share price, issues preferred stock with defined voting and liquidation rights, and updates the company’s Articles of Incorporation. A convertible promissory note or SAFE (Simple Agreement for Future Equity) defers valuation to a future round via a valuation cap and discount rate (typically 15% to 25%). At the growth stage, however, convertible notes carry debt maturity dates and interest; if a company fails to raise a subsequent priced round before maturity, note holders can demand repayment or force a distressed restructuring.
How long does it take to close growth funding from initial outreach to wire?
A priced growth equity round takes 14 to 24 weeks on average: 6 to 10 weeks for partner pitches and term sheet negotiation, followed by 6 to 12 weeks for legal documentation, quality-of-earnings (QoE) accounting audits, and regulatory filings. Senior venture debt or commercial credit facilities close faster, averaging 6 to 10 weeks from term sheet to funding.
Does raising venture debt require a personal guarantee?
Institutional venture debt and recurring revenue lines for Delaware C-Corporations do not require personal guarantees from founders. Instead, the lender files a UCC-1 financing statement taking a blanket senior security interest across all corporate assets (sometimes excluding intellectual property via a “negative pledge on IP”). Conversely, SBA 7(a) and 504 loans strictly mandate personal guarantees from all 20%+ equity owners.
What do you feel about this post?
Like
Love
Happy
Haha
Sad
Angry

I am an independent writer and digital researcher tracking everyday trends, tech shifts, and modern culture across the US. I focus on cutting through internet noise to bring you crisp, honest stories and practical takeaways you can actually use.